Evolution is happy with its financials for Q4 2025 and FY 2025; however, year-on-year declines in profits and revenues follow the current trend we are seeing from most stock-related gambling companies, which is downward. Despite a €1,062.1 million profit in 2025, 2026 will be a challenging year for Evolution, as the industry faces headwinds in restoring investor confidence.
Key Highlights
- Overall 2025 profit of €1,062.1 million, a YoY decline of -14.6%
- A 2025 net revenue growth of +0.2%, a rise in revenue compared to 2024
- 2025 Operating revenue declines -4.3% YoY, compared to 2024
- Evolution CEO says it was a strong year, despite setbacks
- Profits are strong compared to 2022 and 2024, despite the 2025 Vs 2024 decline
Evolution Faced Setbacks in 2025
Overall, Evolution reported declines across all measurable financial figures for Q4 2025, but still turned a profit for the year, which is what all companies aim to do. The only downside is that profits declined by 14.6%, from €1,244.0 million in 2024 to €1,062.1 million in 2025. However, if we look back historically, profits in 2023 were €1,070.9 million, so only marginally better, and in 2022, €843.4 million, so there’s no denying the success of the overall business. Right now, the profit declines are not yet ringing any alarm bells.
Overall, the only conclusion from 2025 is that the company faced significant pressure. If we see a second year of declines, especially profits dropping to 2022’s level, then year three would be a good time to watch the company more closely.
However, with Evolution’s current market reach, which is has a presence in about every online casino I’ve reviewed either via its Evolution live dealer games or NetEnt, Red Tiger, Big Time Gaming and Nolimit City brands, I can’t see the company losing ground.
Yes, we can see that net revenues are overall flat, but looking at the tables below, profit and EBITDA may have declined due to higher operating costs and regulatory headwinds; the company also has expansion costs factored into these figures, and expansion usually yields returns later down the line.
Overall, Evolution is a profitable business, with €1.25 billion in operating cash flow and a strong cash position at year-end, indicating that the core business is intact.
| Year | Profit for the Year |
|---|---|
| 2006–2014 | Not publicly disclosed (private company) |
| 2022 | €843.4 million |
| 2023 | €1,070.9 million |
| 2024 | €1,244.0 million |
| 2025 | €1,062.1 million |
You can read the full Evolution Q4 2025 and 2025 FY report directly on the Evolution’s investor centre. As for the main report released by the software provider, you can read or download the PDF here – Year-end report | January–December 2025 directly from Evolution’s website.
Evolution 2025 Q4 Financial Stats
| Metric | 2025 | YoY Change vs 2024 |
|---|---|---|
| Net Revenues | €2,066.5m | +0.2% |
| Total Operating Revenues | €2,118.2m | -4.3% |
| EBITDA | €1,417.3m | -9.2% |
| Adjusted EBITDA | €1,365.7m | -3.2% |
| Profit for the Year | €1,062.1m | -14.6% |
| Earnings per Share | €5.24 | -11.8% |
Evolution 2025 Financial Year Stats
| Metric | FY 2025 | Notes |
|---|---|---|
| Net Revenues | €2,066.5m | Live + RNG revenues |
| Total Operating Revenues | €2,118.2m | Includes other operating income |
| EBITDA | €1,417.3m | IFRS EBITDA |
| Adjusted EBITDA | €1,365.7m | Excludes earn-out adjustments |
| EBITDA Margin | 66.9% | Based on total operating revenue |
| Adjusted EBITDA Margin | 66.1% | Based on net revenues |
| Operating Profit (EBIT) | €1,257.3m | Before financial items |
| Profit for the Year | €1,062.1m | After tax |
| Profit Margin | 50.1% | Of total operating revenue |
| Earnings per Share | €5.24 | Before dilution |
| Operating Cash Flow | €1,255.2m | Cash from operations |
| Cash & Cash Equivalents | €818.0m | Year-end balance |
| Employees (FTE) | 16,243 | As of 31 Dec 2025 |
Stock Price Declines
The latest figures align with our overall casino news report on shaky iGaming stock in 2025. As the company reported YoY declines for Q4 2025, its stock fell from its Q4 opening price of 765.40 to 629.80 by the end of the quarter and opened at 624.20 for 2026.
With the latest Q4 2025 financial report now out, the stock has reached a new 6-year low of 550. The last time the company’s stock price was at this level was in mid-May 2024, just before Evolution’s stock price began a bull run.
Although the report doesn’t help restore investor confidence, I wouldn’t attribute the latest drop in stock price entirely to the Q4 2025 financial report, as the stock has been on a steady decline since the year began.
Evolution released its 2025 Q4 financial report on 5 February 2026, so it’s still too early to tell whether the report will mean further price declines in the company’s stock value.
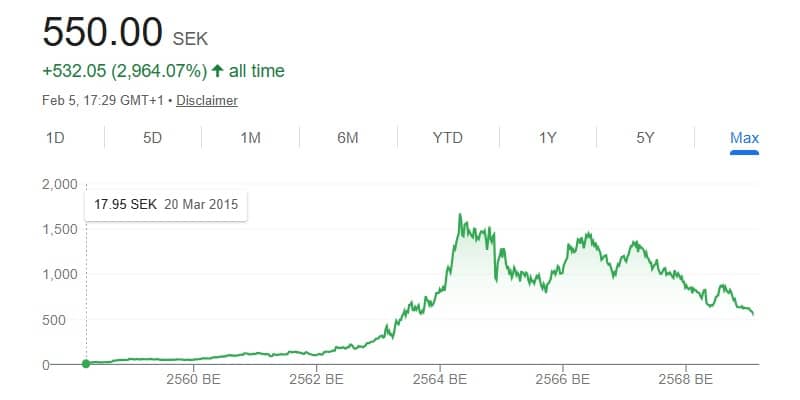
Image courtesy of Google Finance
Casinoplusbonus Opinion
We’ve analysed our fair share of financial reports over time, and Evolution’s may, at first glance, look concerning if you judge the company by a single quarter of YoY decline or a lower profit margin after one below-average year. It’s also difficult not to judge a company that releases public financial statements by its ever-declining stock price. We have to factor in all these points when assessing the success of any business, whether or not it is in gambling. However, I am sweeping these stats under the rug for now because, based on experience, I don’t see Evolution declining much further.
Profits are still high, cash flow is stable, and market conditions across Europe, and in regulated markets elsewhere,e are constantly changing. Also, I am factoring in that Evolution has invested in expansion throughout 2025, and I expect the company’s future quarterly reports, post-Q1 2026, to begin reflecting higher revenue and profits from these investments. Furthermore, I make a judgment call: as an experienced online casino site reviewer, I see Evolution and its online slot brands available at every online casino I review or play at. Therefore, I am reasonably confident Evolution is a sleeping giant waiting to wake up. Its past growth and strategy have always been solid, and I don’t see that changing now.
The company will need to adapt to regulatory changes, which it has demonstrated it is well positioned to do, and continue its growth in an already expanding overseas online casino market, where more online gambling sites operate under Anjouan, Tobique, Curaçao, and Costa Rican licensing. Another key test now is whether the company will grow in emerging markets and continue expanding in the US.
If it can get all these point right over the course of 2026, the software provider could report some it highest profits yet.